





Commercial & development
Finance for property that combines commercial and residential use
A semi-commercial mortgage, also known as a mixed-use mortgage, finances a property containing both commercial and residential space. A familiar example is a shop with a flat above on the same title. These properties sit between conventional buy-to-let and fully commercial lending, so the correct mortgage depends on the use, occupants, income, leases, layout and ownership structure.
We will assess your complete circumstances, explain the available routes and recommend a mortgage that supports your wider plans. Your initial conversation is without obligation.
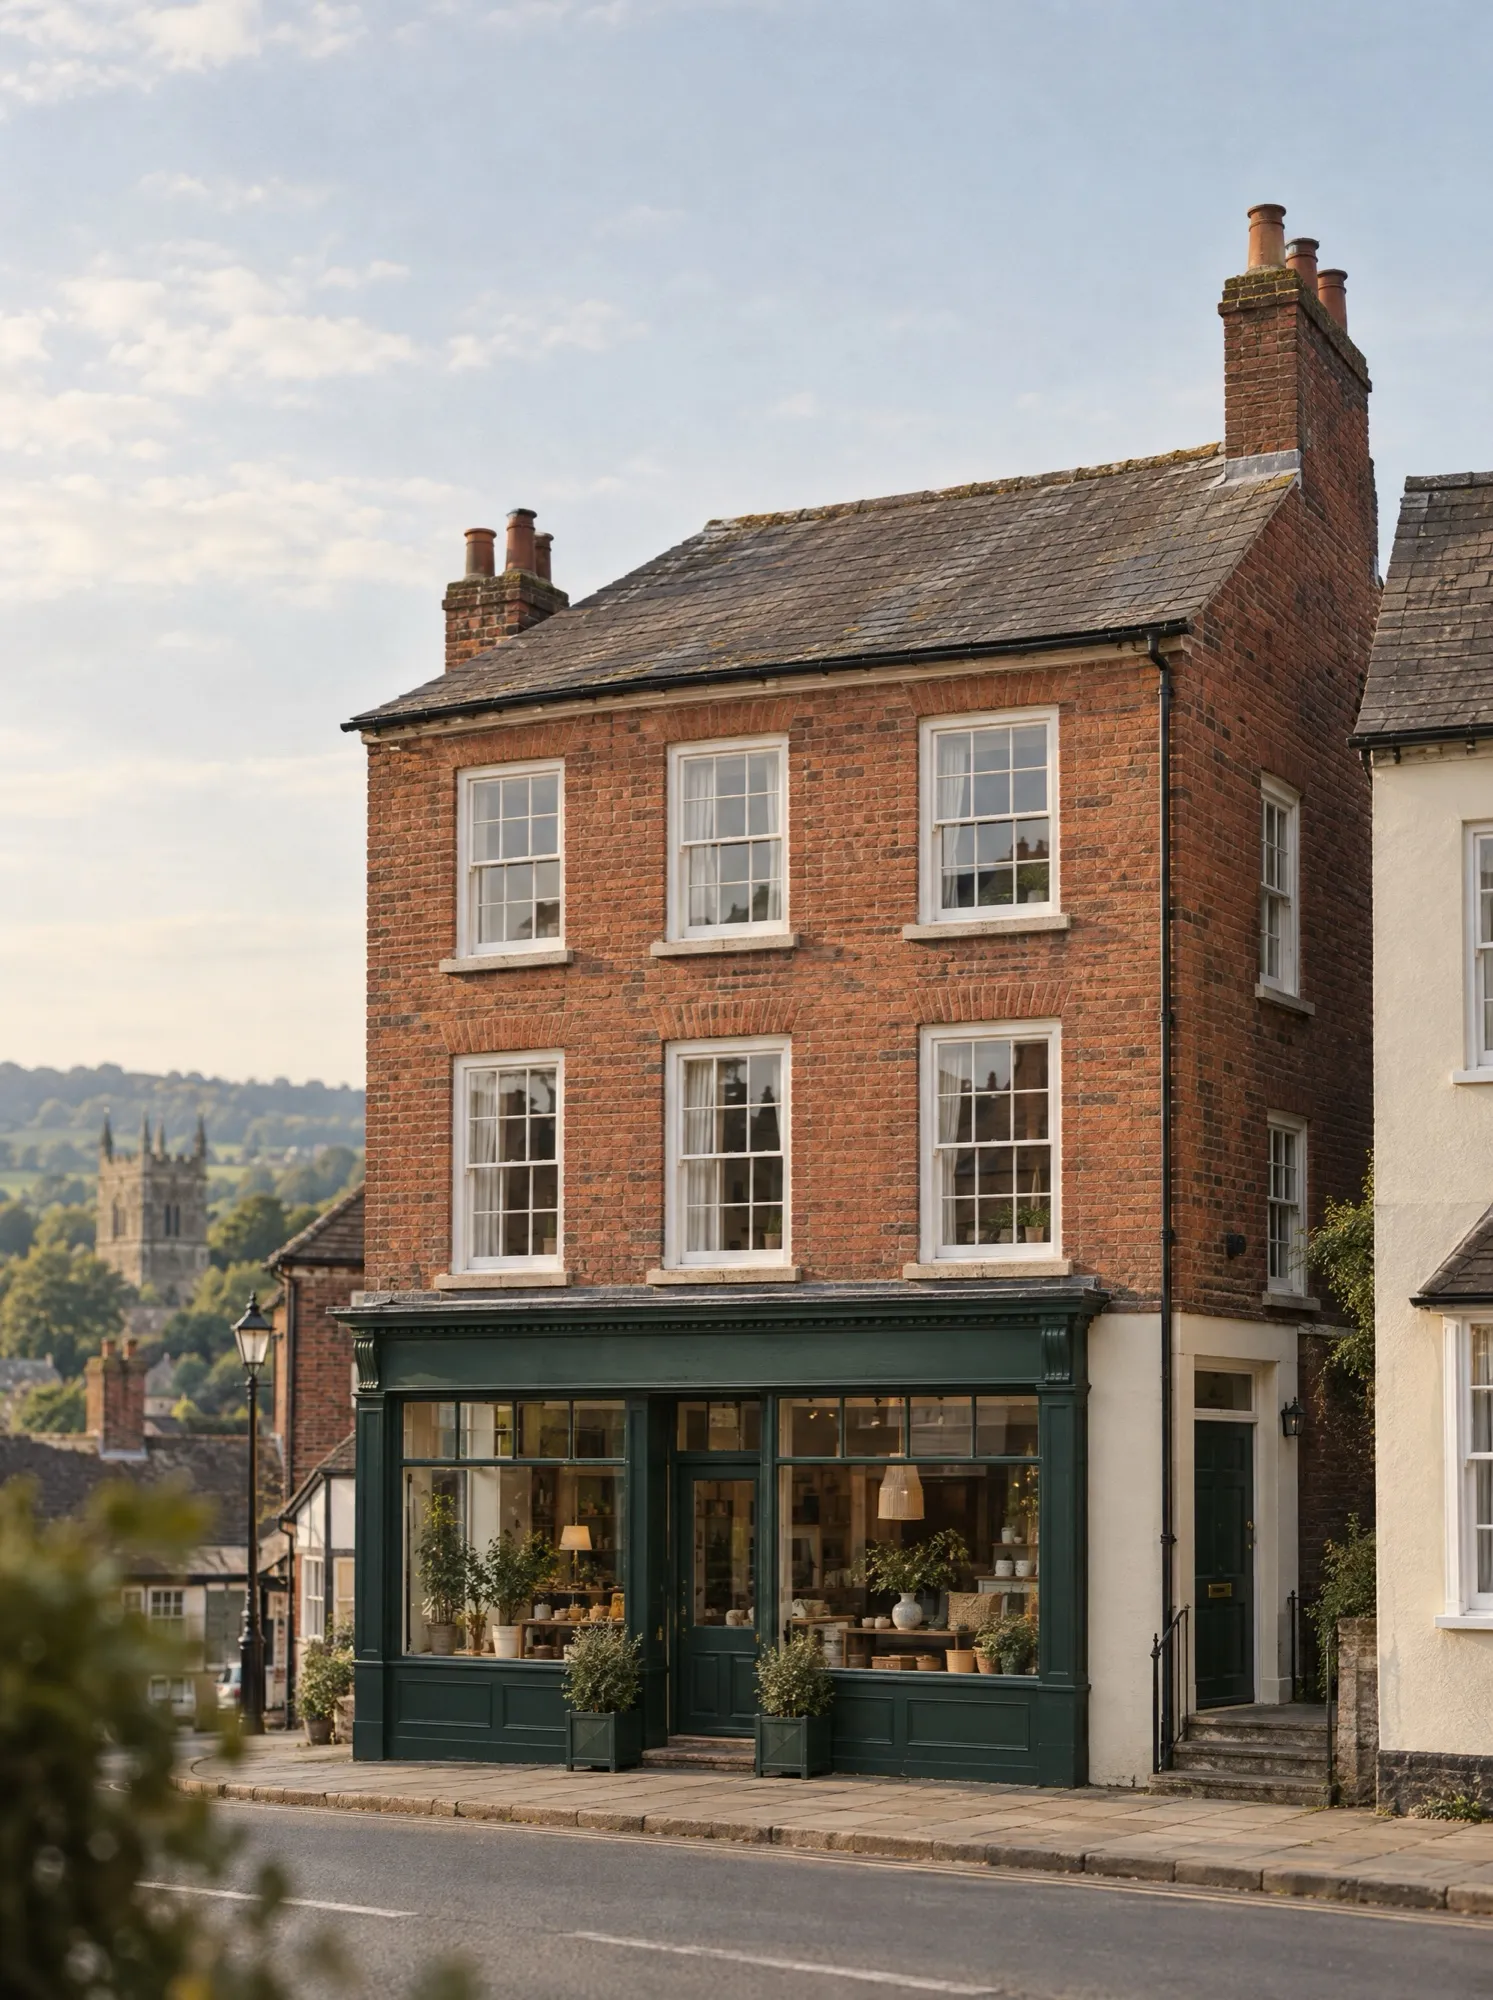
A shop and flat on one title
An investor purchasing the freehold of a ground-floor shop with a self-contained flat above is buying one mixed-use asset. The lender considers the commercial tenant and lease, the residential tenancy, access to each unit, combined income and the property’s marketability. If the flat is on a completely separate leasehold title and only that flat is being purchased, the appropriate mortgage may instead fall within specialist residential or buy-to-let criteria.
Who this may help
We help landlords purchasing or refinancing mixed-use investments, trading businesses buying premises with residential accommodation, property companies raising capital, and clients restructuring assets held personally, through a partnership, LLP, SPV or trading company. Typical properties include shops or offices with flats above, mixed retail and residential freeholds, pubs or guest houses with accommodation, and other buildings with distinct business and living areas.
What needs to be considered
- Whether the whole property is held on one title or separate titles
- The proportion, layout and permitted use of the commercial and residential areas
- Separate access, services and marketability of each element
- Investment, owner-occupied or partly owner-occupied use
- Commercial lease terms, tenant quality, passing rent and remaining lease length
- Residential tenancy, market rent and occupancy
- Business trading history, accounts and sustainable profit for owner-occupiers
- Property value, vacant-possession value, investment value and loan-to-value
- Borrower experience, credit profile, ownership structure and personal guarantees
- Planning use, licences, property condition, EPC and mixed-use insurance
How ERG Finance approaches it
ERG Finance first establishes exactly what is being mortgaged and how every part of the property will be used. We then assess the rental or trading-income route, review the leases and accounts, and identify the lenders whose definition of semi-commercial matches the asset. We compare rate, fees, valuation basis, repayment structure and flexibility before preparing the application for the lender, valuer and solicitor.
Investment and owner-occupied cases are assessed differently
For an investment property, the lender normally tests income from the commercial and residential units against the proposed debt. Passing rent, market rent, lease quality, voids and the tenant profile can all influence the result. For an owner-occupied property, the trading business must demonstrate that it can service the mortgage, commonly through accounts and an assessment of sustainable profit or EBITDA. Where part of the building is let, that rental income may also be relevant. A business with limited trading history or a vacant unit is not automatically excluded, but lender choice and evidence become more important.
Our role
- understand the purpose of the mortgage and the outcome you need
- check affordability, lender criteria and property requirements before recommending a route
- compare the rate, fees, flexibility, early repayment charges and overall cost
- prepare the application and evidence so the lender sees a complete and accurate case
- manage the mortgage process through valuation, offer and completion
Frequently Asked Questions
-
It is a mortgage secured against a property containing both residential and commercial elements. It is also commonly called a mixed-use mortgage.
-
Usually, if you are buying the whole building on one title. If you are purchasing only a separately titled flat above commercial premises, it may instead require a residential or buy-to-let mortgage from a lender comfortable with the neighbouring business.
-
A deposit of 25% or more is common, although the required contribution depends on the property, use, income, experience, credit profile and valuation. A lower maximum loan-to-value may apply to specialist sectors, vacant units or weaker locations.
-
Investment cases are usually assessed against the rent and debt-service calculation for the whole property. Owner-occupied cases rely more heavily on the trading business’s sustainable profit and ability to meet payments. The property value can restrict the loan even where income is strong.
-
A commercial valuer considers the asset as a whole, including its uses, leases, rents, location, condition and saleability. The lender may restrict borrowing by reference to the lower of the purchase price and one or more valuation measures, rather than simply adding together separate residential and commercial estimates.
-
Yes. Options can exist for limited companies, SPVs, trading companies, LLPs, partnerships and personal ownership. The lender will review the ownership structure, directors, shareholders, guarantees and source of funds.
-
Not necessarily. Occasional home working or a small office may remain acceptable under a residential mortgage. A distinct business area, customer visits, structural alterations, specialist use or a material commercial proportion requires closer assessment and the existing lender’s consent.
-
Many mixed-use investment and commercial facilities are not regulated by the Financial Conduct Authority. However, regulatory status depends on the borrower, ownership, residential proportion and intended occupation. ERG Finance will establish the correct status before making a recommendation.
-
Pricing depends on loan-to-value, property and tenant type, lease strength, location, experience, credit profile, income coverage and repayment basis. The arrangement fee, valuation, legal work and early repayment terms should be compared alongside the interest rate.
You might also need
Speak to an advisor
Book a consultation
Check out our availability and book the date and time that works for you.
Select a Date and Time
Time zone: United Kingdom (Europe/London)
Your consultation
A 30-minute telephone call with one of our advisers. Tell us a little about your situation and we’ll match you with the right person.
Select a date to see availability
Booking Form
Your consultation is booked.
A confirmation will follow by email. Need to make a change? Call +44(0) 1743 668 202.
This booking was taken in test mode and has not reached our diary. Please call 01743 668 202 to confirm your appointment.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR OTHER DEBT SECURED ON IT. Buy-to-let mortgages and commercial lending are not usually regulated by the Financial Conduct Authority. The regulatory status of mixed-use borrowing depends on the borrower, ownership structure, residential use and intended occupation; ERG Finance will establish the position as part of its assessment.