





Residential & specialist
A mortgage arranged around the deadlines and details of a new-build purchase
Buying a newly built home can involve reservation deadlines, developer incentives and a completion date that is not yet fixed. Lenders also apply specific rules to new-build valuations, warranties, leasehold terms and maximum loan-to-value. Early assessment reduces the risk of discovering a problem after the reservation fee is paid.
We will assess your complete circumstances, explain the available routes and recommend a mortgage that supports your wider plans. Your initial conversation is without obligation.
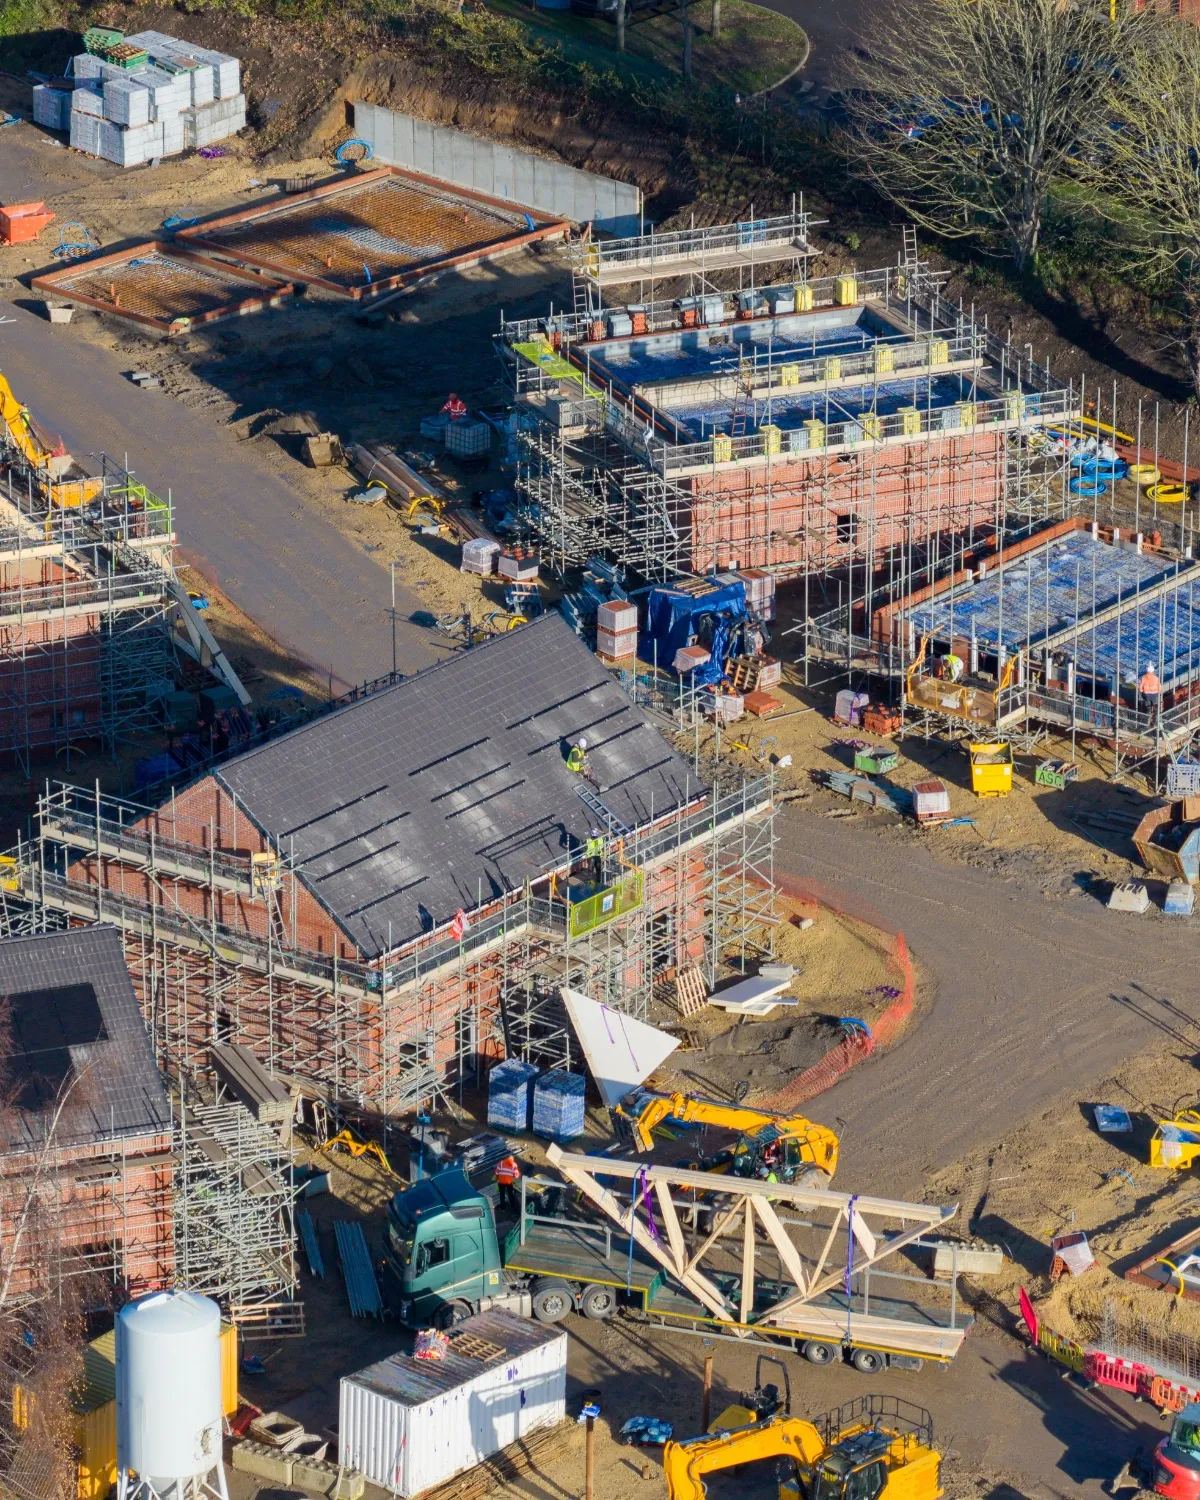
Why lenders treat new-build homes differently
A lender may define a property as new build for a period after construction, conversion or first occupation, or whenever it is sold by the developer. New-build flats and houses can have different deposit requirements. The valuation is based on the property’s mortgageable value and may not match the headline price once incentives are considered.
Who this may help
We help first-time buyers, home movers and investors purchasing houses, flats, conversions and off-plan property. We can also assist with high-value new homes, non-standard construction, long build periods and applications where the mortgage offer may need extending or revisiting before completion.
What needs to be considered
- The reservation deadline and expected build-completion window
- Mortgage-offer validity and the lender’s extension policy
- Deposit requirements for houses compared with flats
- Cashback, gifted deposits, upgrades and other developer incentives
- The valuation and the risk of a down valuation
- An acceptable new-build warranty or professional certificate
- Lease length, ground rent, service charges and estate charges
- Fire-safety, cladding and building-regulation evidence for flats
- Construction method and lender acceptance
- Snagging, long-stop dates and protection if completion is delayed
How ERG Finance approaches it
We check the development, property type, deposit, incentives and likely completion date before selecting a lender. We also remain alert to product changes and offer expiry during the build. Your conveyancer must separately confirm title, warranty, lease and contract matters.
Developer incentives and valuation
Incentives must be disclosed. They can include cashback, deposit contributions, payment of fees, upgrades or other benefits. Lenders differ in what they accept and may base the mortgage on the lower of purchase price or valuation after considering incentives. A generous package does not automatically increase the amount that can be borrowed.
Our role
- understand the purpose of the mortgage and the outcome you need
- check affordability, lender criteria and property requirements before recommending a route
- compare the rate, fees, flexibility, early repayment charges and overall cost
- prepare the application and evidence so the lender sees a complete and accurate case
- manage the mortgage process through valuation, offer and completion
Frequently Asked Questions
-
Offer validity differs by lender and product. Some have dedicated new-build periods or extension processes. The expected completion date should be checked before application.
-
Sometimes. A number of lenders apply lower maximum loan-to-value limits to new-build flats than houses, although the market varies.
-
Many accept incentives within defined limits, but all incentives must be disclosed and can affect the valuation or maximum loan.
-
The lender bases its decision on the valuation it accepts. You may need to renegotiate, increase the deposit, change lender if appropriate or reconsider the purchase.
-
Lenders generally require an acceptable new-build warranty or, in permitted cases, a suitable professional consultant’s certificate. Acceptance varies by lender.
-
Some lenders allow a product change if rates improve, subject to availability and timing. A material change or expired offer can require reassessment.
Speak to an advisor
Book a consultation
Check out our availability and book the date and time that works for you.
Select a Date and Time
Time zone: United Kingdom (Europe/London)
Your consultation
A 30-minute telephone call with one of our advisers. Tell us a little about your situation and we’ll match you with the right person.
Select a date to see availability
Booking Form
Your consultation is booked.
A confirmation will follow by email. Need to make a change? Call +44(0) 1743 668 202.
This booking was taken in test mode and has not reached our diary. Please call 01743 668 202 to confirm your appointment.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE. The availability and terms of any mortgage depend on individual circumstances, lender criteria, affordability, credit assessment and valuation.