





Insurance
Protect the property while it is being transformed.
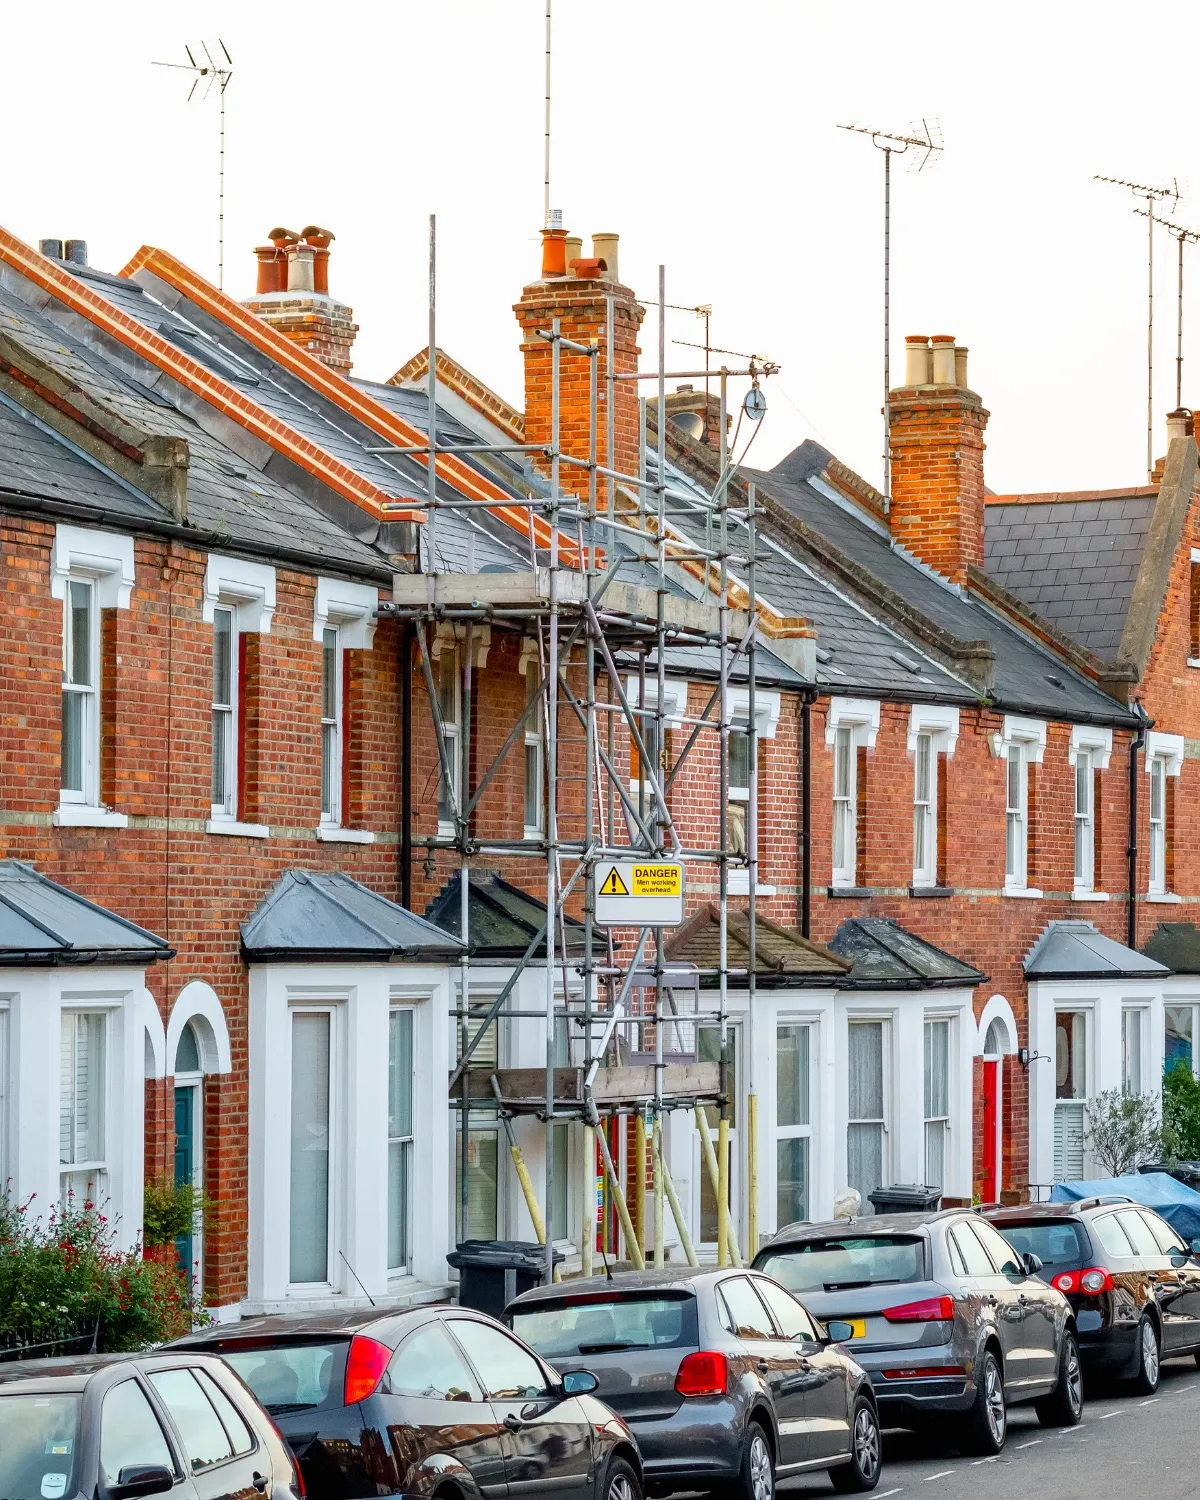
Major renovation work can take a property outside the limits of an ordinary home or landlord policy. Structural alterations, contractors, scaffolding, exposed roofs and periods of unoccupancy all change the risk.
We can consider the insurance at the same time as the finance, so cover is understood before work begins and remains aligned with the project through to completion.
Tell the insurer before work starts
Homeowners and landlords should not assume that an existing policy will continue unchanged during major works. Some policies restrict structural alterations, limit cover when the property is empty or require the insurer's written agreement before work begins.
The safest point to review cover is before contracts are signed and before contractors attend site. We will establish the scope, value and duration of the works, the occupancy position and the insurance already held by the owner and contractor.
What renovation insurance may need to protect
- The existing structure before work begins.
- The contract works as they progress.
- Materials kept on site or awaiting installation.
- Damage caused by insured events during the project.
- Property owners' liability and other relevant liabilities.
- Periods when the property is unoccupied or not weather-tight.
- Alternative accommodation or loss of rent where specifically included.
Both arrangements need to be understood
The exact cover depends on the contract and policy. Contractors' insurance does not automatically protect the property owner's full interest, so both arrangements need to be understood rather than assumed.
Renovation, bridging and development finance
Renovation projects often involve a short-term bridge, staged development facility or a refinance after works. We can consider the funding and insurance together, including the lender's requirements, the works programme and the planned exit.
Once the property is complete and occupied, the renovation policy should be replaced by appropriate household or landlord cover. We can keep that transition on the project plan rather than leaving it until the last day.
Listed and high-value renovation
Listed and historic buildings require particular care. Specialist materials, heritage approvals and skilled labour can materially increase the cost and duration of reinstatement. The sums insured and policy conditions should reflect the building before work begins and the completed value of the works.
Information we will need
- Property address, construction, age, listed status and current condition.
- The value of the existing structure and an appropriate rebuilding cost.
- A schedule and value of works, including professional fees and contingency where relevant.
- Expected start date, duration and target completion date.
- Details of structural work, excavation, roofing and other higher-risk activity.
- Contractor experience, contract terms and insurance arrangements.
- Occupancy, security, utilities and inspection arrangements during the works.
Home & Property Insurance
Frequently Asked Questions
-
Minor decorative work may be acceptable, but major or structural work can be restricted or excluded. The existing insurer should be told before work begins.
-
Not necessarily. The builder's liability and contract works insurance may not protect the owner's full interest in the existing structure. The contract and both policies need to be checked.
-
Specialist cover can be available, but security, inspection, heating and other conditions may apply. Full details of the unoccupancy must be disclosed.
-
The renovation policy should be reviewed and replaced by suitable owner-occupied or landlord cover. The completed rebuilding cost, occupancy and contents should be updated.
Arrange the cover before the first wall comes down.
Talk to us when the scope and funding are being planned. We will gather the information, explore appropriate cover and keep the policy aligned with the finance and works timetable.
Request a renovation insurance quoteCover is arranged through our insurance sourcing arrangements, subject to underwriting and eligibility.
The information on this page is general guidance. Insurance is subject to underwriting and the terms, conditions, limits, exclusions and excesses of the selected policy. Full details will be provided before you decide whether to proceed.