





£3.75 Million Refinance of a Prime Cheshire Home Using the Latest Year’s Net Profits
Self Build Refinance · Cheshire
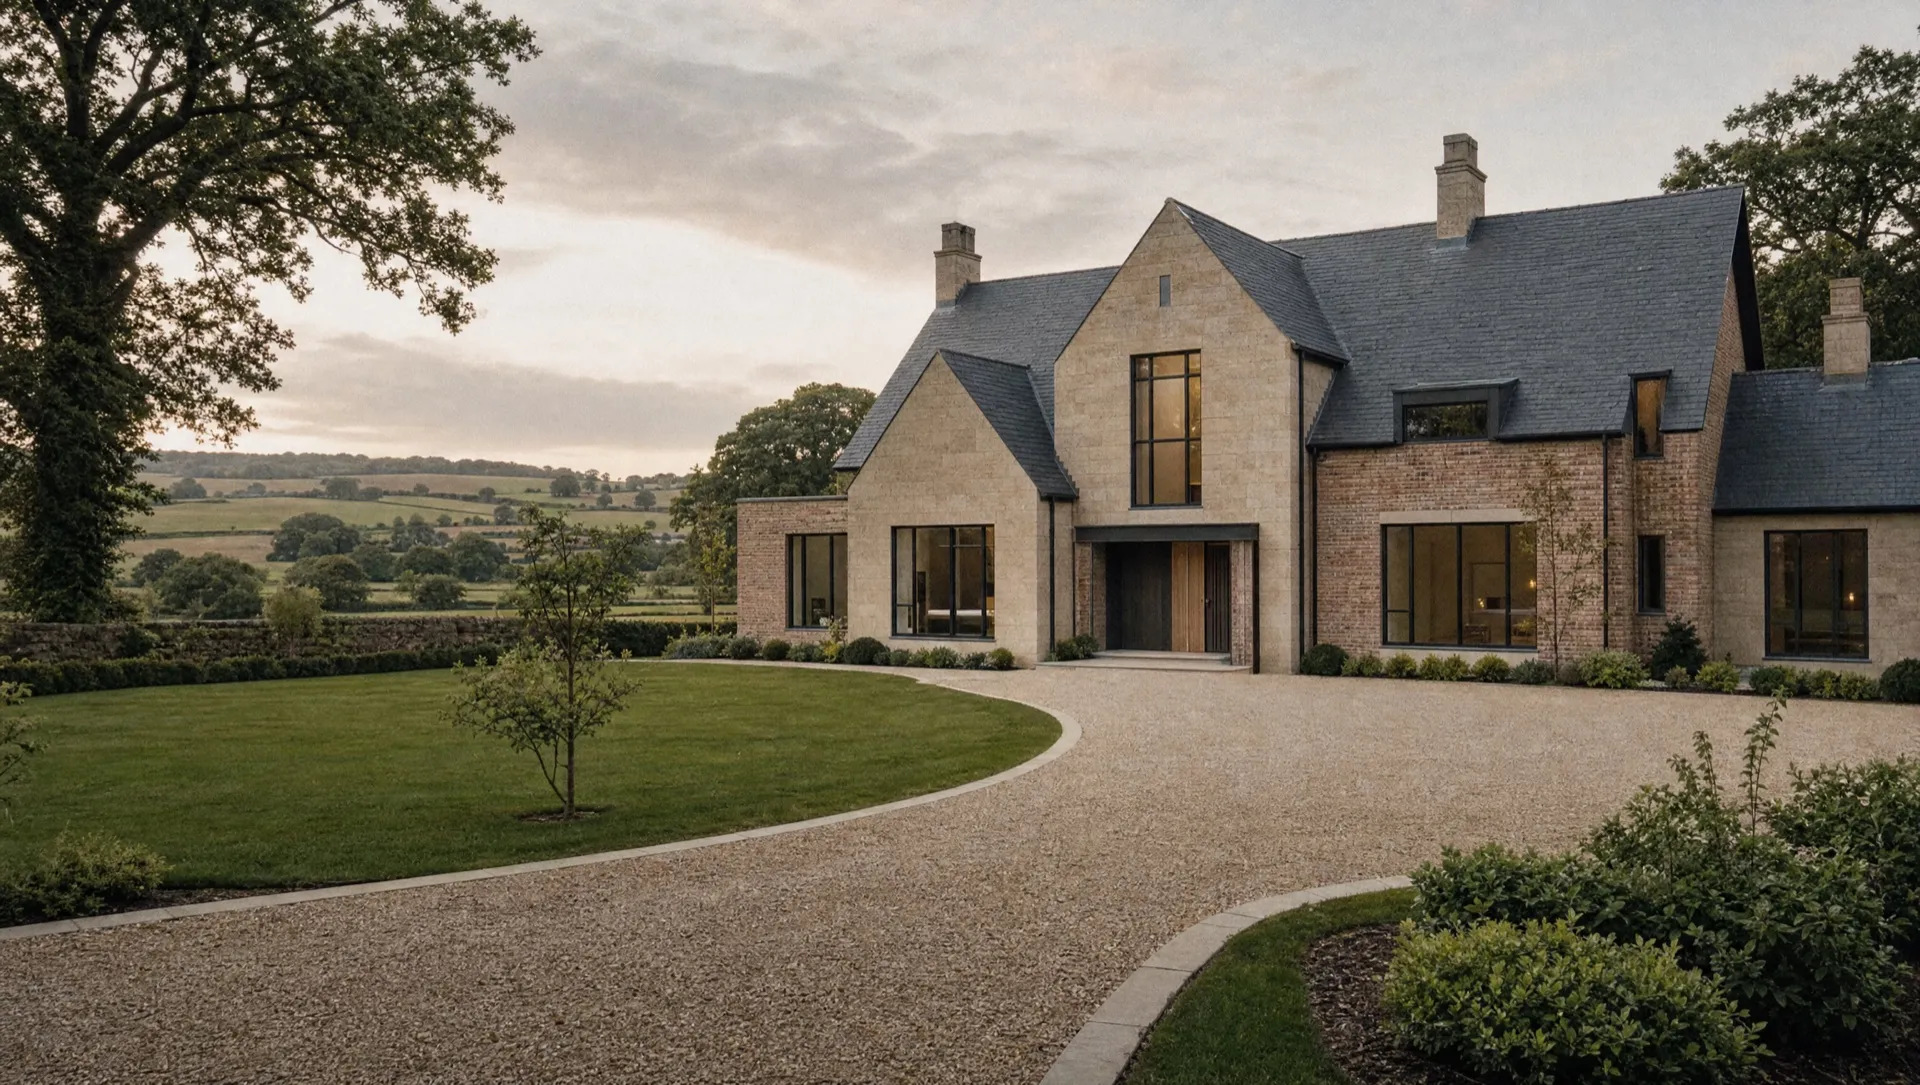
A £3.75 million residential refinance of a newly built Cheshire home, assessed on the latest year’s business net profits and structured mainly on interest only.
The Scenario
Having arranged the original self build mortgage, we were approached again as our client’s new home in Cheshire neared completion.
The property had been valued at approximately £5 million. The next step was to move from the self build facility onto a residential mortgage, securing a lower interest rate and replenishing some of the savings invested in the construction.
The client required borrowing of approximately £3.75 million, representing 75% of the property’s value. They wanted the majority of the mortgage on interest only, with a five year fixed rate to provide certainty over monthly payments.
The Challenge
There were several considerations beyond simply finding a competitive rate.
Firstly, we needed a lender prepared to assess affordability using the latest year’s business net profits, rather than relying solely on the income the client had personally drawn. This was central to supporting the level of borrowing required.
Secondly, the first remortgage following a self build can be more restrictive than clients expect. Some high street lenders would not consider the property directly from the self build facility, even though they might consider it at a subsequent remortgage.
Timing also mattered. Interest rates were rising, but the property had not yet reached practical completion. Waiting until every element of the build was finished risked losing the available mortgage product.
At this level of borrowing, even a small movement in interest rates can make a substantial difference to the cost.
Our Solution
We identified a lender whose approach accommodated the client’s business income, the loan size and the first refinance following a self build.
Using the latest year’s net profits allowed the affordability assessment to reflect the business’s recent performance, rather than being limited to the amounts the client had withdrawn personally.
The mortgage was structured with:
- Approximately £3.75 million of borrowing, against a property valued at £5 million.
- Around £3.25 million on interest only, with approximately £500,000 on capital repayment.
- A five year fixed rate, providing certainty over the initial fixed rate period.
- Funds to repay the self build mortgage and replenish savings invested in the project.
We also arranged for the valuation to take place before practical completion had been reached. The valuer took a pragmatic view of the property’s stage of construction, allowing the application to progress while the remaining works were finished, subject to the lender’s completion requirements.
This helped us move the application forward and secure the selected rate during a period of rising mortgage pricing.
The Outcome
We arranged a residential refinance that brought together the client’s key objectives: a lower interest rate, borrowing assessed using the latest year’s business profits, and a mortgage structured predominantly on interest only.
The arrangement also allowed the client to recover some of the personal funds committed to creating their home.
Having supported the original self build, we understood the project and could plan the transition to longer term finance as completion approached.
This case demonstrates the importance of matching the lender to the whole requirement. The income assessment, property history, repayment structure and timing all mattered.
Completing a self build or looking for a lender who understands your business income? Speak to ERG Finance about your next step.
Facing something similar?
Book a Consultation