





Mixed-Use Freehold Investment: Residential Apartments + SIPP Commercial Unit
Mixed-Use / SIPP · Shropshire / Worcestershire
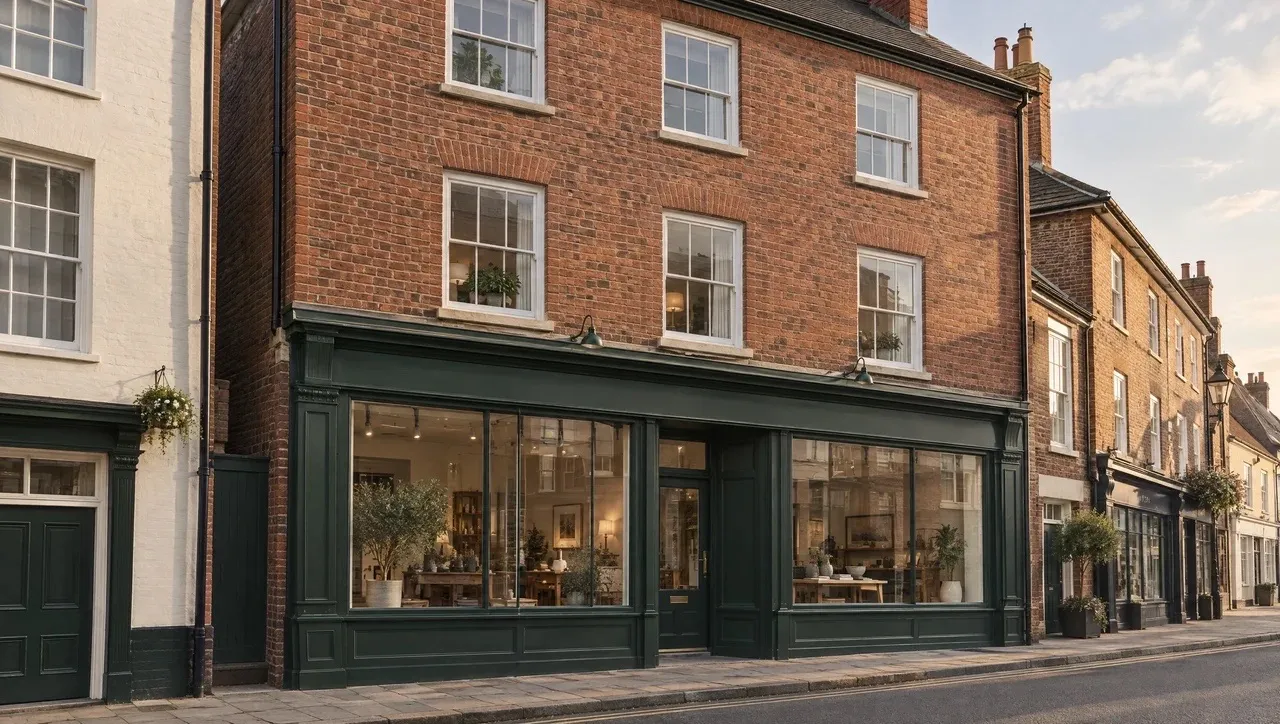
How ERG Finance structured a £372,500 mixed-use freehold purchase — three apartments through a limited company SPV, and the commercial unit acquired by the client's SIPP.
The Scenario
Our client was looking to purchase a mixed-use freehold building in a Shropshire/Worcestershire border location.
The property comprised three self-contained residential apartments, together with a ground floor retail unit and basement. The agreed purchase price for the whole building was £372,500.
Rather than purchasing the building as one straightforward mixed-use investment, the client wanted to structure the transaction in two parts:
- The three residential apartments would be purchased through a new limited company SPV.
- The commercial element would be acquired by the client’s SIPP on completion.
The three residential apartments were already let on assured shorthold tenancies. The commercial unit was also let, with the tenant indicating willingness to extend the lease term.
This was a highly attractive investment opportunity, but the structure required careful planning from the outset.
The Challenge
This was not a standard buy-to-let purchase.
The client was acquiring a mixed-use freehold building, but the lender’s security would only relate to the residential element and the relevant freehold interest. The commercial unit was being separated and acquired by the SIPP on the same day as completion.
That created several moving parts:
- The lender needed to understand exactly what formed its security.
- The valuer needed clear instructions to value the three residential apartments and freehold interest, excluding the commercial element being acquired by the SIPP.
- The solicitor needed to confirm that the simultaneous purchase and transfer structure could be completed correctly.
- The lender needed to be comfortable with a multi-unit freehold block above commercial premises.
Many lenders would either decline this type of structure or struggle to understand how the transaction fitted together.
Our Solution
ERG Finance worked to present the transaction clearly and logically. The key was to separate the transaction into its component parts, rather than treating it as one conventional mixed-use purchase.
The commercial unit was a natural fit for the client’s SIPP, as the client already held pension funds that could be used to acquire the commercial premises. Once completed, the commercial rent would be payable to the SIPP, supporting the client’s wider pension investment strategy.
The residential apartments were structured through a limited company buy-to-let mortgage. This gave the client a clear investment vehicle for the residential element and allowed the lender to assess the case as a specialist multi-unit freehold block transaction.
We also helped position the wider funding strategy, including the use of equity from another property to support the residential deposit, purchase costs and contingency.
This meant the lender could assess the residential element clearly, while the SIPP acquisition of the commercial premises was handled separately with the relevant legal and pension advice.
The Outcome
By presenting the case properly, the transaction became understandable and fundable.
The structure allowed the client to:
- Acquire the full mixed-use building.
- Use SIPP funds to purchase the commercial element.
- Hold the residential apartments within a limited company SPV.
- Secure specialist MUFB buy-to-let lending.
- Borrow on an interest-only basis to support cash flow.
- Retain a clear separation between the pension-owned commercial asset and the limited company residential investment.
This was a strong example of where specialist advice added genuine value.
The opportunity was not just about finding a mortgage rate. It was about understanding the property, ownership structure, pension element, valuation requirements, deposit strategy and lender appetite — then presenting the whole case in a way that made sense.
Conclusion
Complex property transactions often fail because they are not structured or explained clearly.
In this case, the individual parts of the transaction were all logical, but they needed to be brought together carefully. The lender needed clarity on its security, the solicitor needed to be comfortable with the completion mechanics, and the client needed a funding strategy that made the wider purchase work.
This case demonstrates how ERG Finance helps clients and introducers navigate more complex property transactions, particularly where standard lending routes are not obvious.
If you are looking at a mixed-use property, a multi-unit freehold block or buy-to-let, commercial premises, or a limited company buy-to-let structure, we would be happy to help review the numbers and consider the most suitable route. Speak to a specialist about your transaction.
This case study is for illustrative purposes only and is based on a specific client scenario. Lending is subject to status, lender criteria, valuation and full underwriting. ERG Finance does not provide taxation, pension or legal advice, and clients should seek appropriate professional advice where required.
Facing something similar?
Book a Consultation